
Broadcom (AVGO) is about to release its latest earnings report, and Goldman Sachs has lowered its 12-month price target from $540 to $460, maintaining a "Buy" rating. James Schneider of Goldman Sachs' semiconductor research team noted in a report published on November 18, 2026, that although the company's recent results and guidance are expected to slightly beat expectations, the key to the stock's direction lies in the visibility of data center deployments in 2028, as well as the custom chip share challenges posed by competitors such as MediaTek.
Results Expected to Slightly Beat, Valuation Cut Lowers Price Target
Market expectations for Broadcom's earnings this time are generally low.
However, driven by the stock's outperformance versus the broader market over the past week, market sentiment has recovered somewhat. Goldman Sachs expects Broadcom's fiscal 2026 fourth quarter (FY4Q26) and fiscal 2027 first quarter (FY1Q27) results and guidance to both slightly beat expectations.
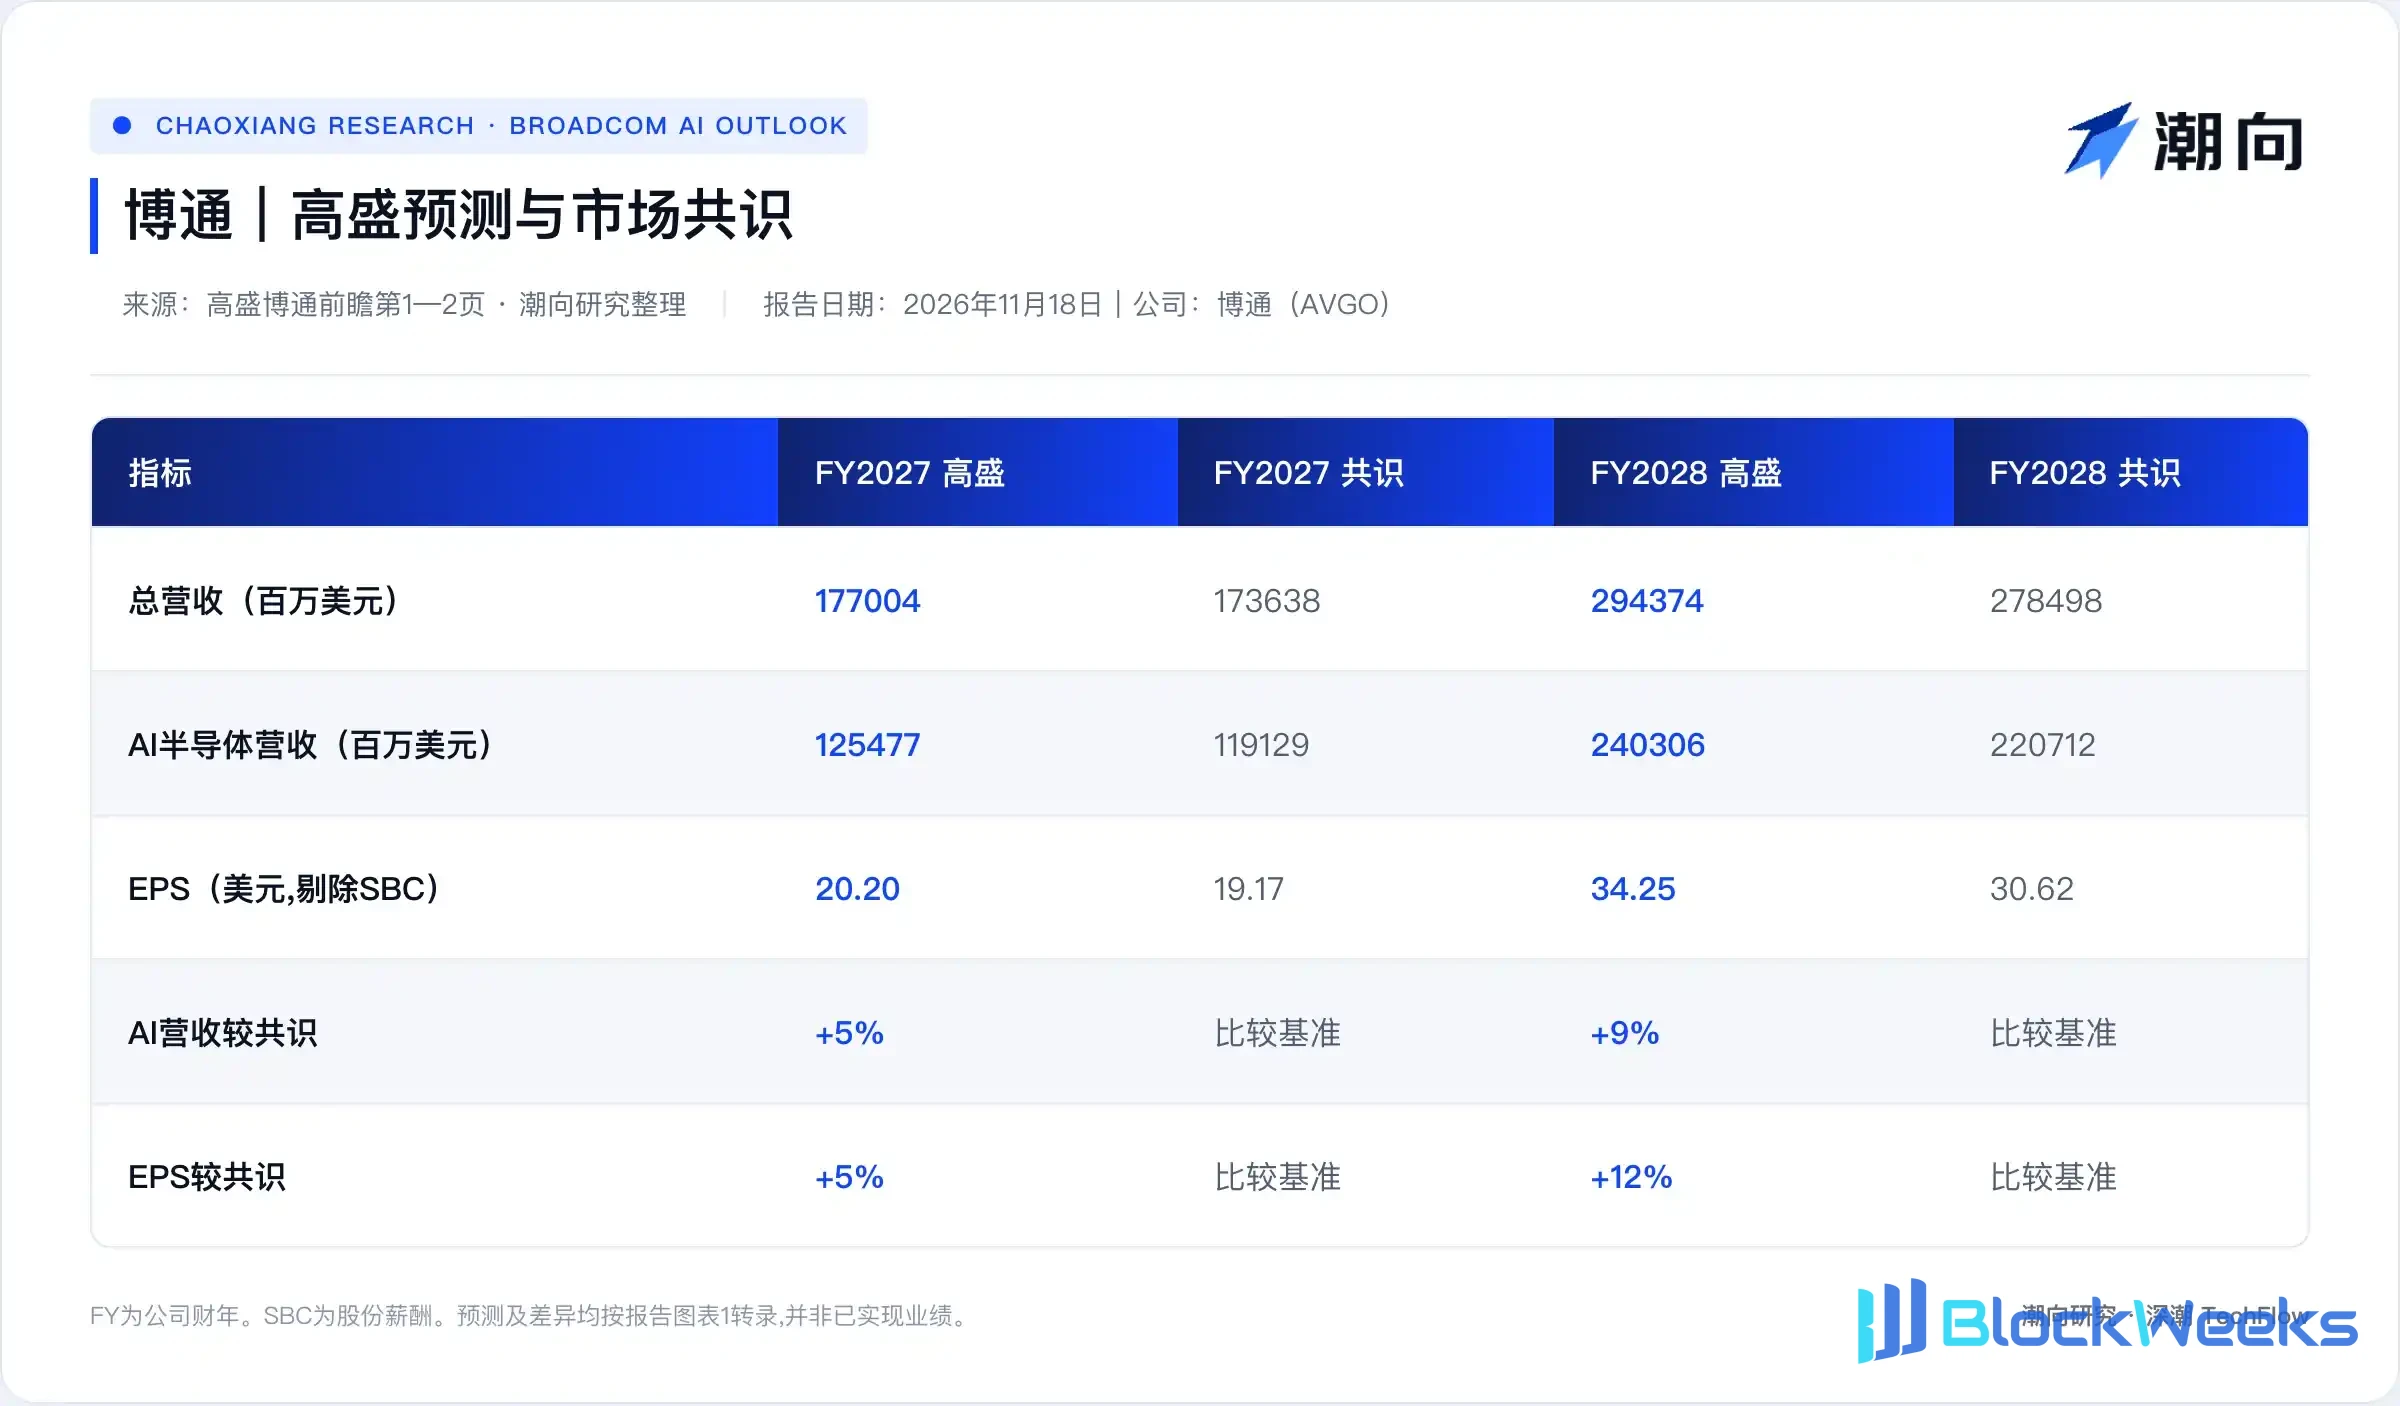
On specific financial forecasts, Goldman Sachs expects Broadcom's total revenue for fiscal 2027 to reach $177.004 billion, above the consensus estimate of $173.639 billion; earnings per share are expected to be $20.20, 5% above consensus. By fiscal 2028, Goldman Sachs expects total revenue to climb to $294.374 billion and earnings per share to reach $34.25, 6% and 12% above consensus, respectively.
Earnings expectations remain strong, yet the price target was cut. Goldman Sachs lowered Broadcom's 12-month price target from $540 to $460, implying 34.7% potential upside (based on the November 17, 2026 closing price of $341.60).
The reason for the cut is a downward shift in peer valuation multiples. Goldman Sachs kept Broadcom's normalized earnings per share forecast of $18.00 unchanged, but lowered the target valuation multiple from 30x to 25x.
New Clouds Support 70% of Custom Chips, Financing and Power Become Variables
Whether the earnings call can provide clearer long-term visibility will directly affect stock price volatility.
The AI business remains Broadcom's core growth engine. Goldman Sachs expects Broadcom's AI semiconductor revenue to reach $125.477 billion in fiscal 2027 and further double to $240.306 billion in fiscal 2028, 5% and 9% above consensus, respectively. Non-AI semiconductors and infrastructure software businesses are relatively flat, with Goldman Sachs' fiscal 2027 revenue forecasts for these two segments 5% and 3% below consensus, respectively.
Underpinning this high growth is a massive custom accelerator chip (XPU) deployment plan, but buyers' funding and infrastructure bottlenecks are raising market concerns.
Goldman Sachs disclosed that of Broadcom's planned approximately 10 gigawatts (GW) of custom XPU deployments for fiscal 2027, emerging hyperscalers account for about 6.3 gigawatts. By fiscal 2028, Broadcom's planned custom XPU deployment target doubles to 20 gigawatts, with emerging cloud providers' share rising further to about 75%.
After the U.S. midterm elections, investors' scrutiny of tight supply of data center land, power, and shell space (LPS) in 2028 has noticeably intensified. Meanwhile, emerging cloud providers are highly dependent on external financing, and the stability of their funding chains is directly tied to whether orders can be delivered on schedule. Goldman Sachs believes that if management can provide substantive details on the earnings call to dispel market doubts about 2027 shipments and the realization of the 2028 20-gigawatt target, it would be an important catalyst for the stock.
MediaTek's Entry Intensifies Competition, Google's Share in Focus
Beyond physical infrastructure and financing constraints, the competitive landscape in the custom chip arena is also changing.
As AI computing demand shifts toward customization, competitors such as MediaTek are accelerating their entry into the ASIC market. Goldman Sachs noted that investors are highly focused on Broadcom's customer stickiness in the next-generation XPU product cycle, especially the stability of share with core major customers such as Google.
If management can further disclose long-term cooperation progress on next-generation custom chip projects, it would help alleviate market concerns about share loss.
Looking ahead to the market's main themes after the earnings release, Goldman Sachs believes investors will continue to focus on two core tensions: first, emerging cloud providers' actual 2027 procurement capacity amid tightening external financing, and second, the progress in alleviating data center power and site bottlenecks in 2028. The report also flagged four downside risks, including a slowdown in AI infrastructure spending, loss of custom computing business share, slower-than-expected inventory digestion for non-AI chips, and intensifying competition facing the VMware software business.

This article is Chaoxiang Research's compilation and interpretation of a third-party brokerage research report. The ratings, price targets, earnings forecasts, and related judgments cited in the article are all the views of that brokerage's analysts, representing only their institution's position, not those of Chaoxiang Research, and do not constitute any investment advice.
Markets carry risk; decisions must be independent. This article should not be used as a basis for buying or selling any securities.




